TLDR
How your home is valued after a loss matters just as much as whether it’s insured. Replacement Cost, Extended Replacement Cost, guaranteed replacement cost coverage, Actual Cash Value, and Functional Replacement Cost all determine how much money actually shows up after damage. Many Kentucky homeowners unknowingly carry valuation methods that reduce payouts. Understanding these differences before a claim is the key to avoiding financial shortfalls.
This week, we’ve been breaking down one of the most misunderstood parts of homeowners insurance:
👉 Valuation.
Not deductibles.
Not premiums.
Not coverage types.
Valuation.
Because when something serious happens, fire, water damage, storm loss, valuation determines whether you rebuild comfortably or scramble financially.
This pillar article pulls together everything we covered this week into one practical guide.
Start With the Baseline: Replacement Cost
Replacement Cost is the foundation of proper home insurance.
It means your policy pays what it costs to rebuild or repair your home using like kind and quality materials, without subtracting for depreciation.
Your aging roof is paid like a new roof.
Your worn flooring is replaced, not discounted.
Your cabinets are rebuilt, not depreciated.
We covered this in detail in Replacement Cost Coverage Explained, including why policy limits still matter even when Replacement Cost is present.
Here’s the key takeaway:
Replacement Cost is essential, but it is not unlimited.
Coverage stops at your dwelling limit unless additional protection exists.
The Safety Net Most People Miss: Extended Replacement Cost (+25% / +50%)
Extended Replacement Cost adds a buffer above your dwelling limit, typically 25% or 50% extra: to absorb unexpected rebuild overruns.
This exists because real-world reconstruction almost never matches the original estimate.
Labor shortages.
Material price spikes.
Code upgrades.
Debris removal.
These costs stack fast.
In Extended Replacement Cost (+25% and +50%) Explained, we showed how a $350,000 home can easily require $400,000+ to rebuild after a major loss, and how Extended Replacement Cost keeps that gap from coming out of your pocket.
Think of it this way:
Replacement Cost is the base.
Extended Replacement Cost is the cushion.
The Gold Standard: Guaranteed Replacement Cost
Guaranteed Replacement Cost removes the ceiling entirely.
If your policy includes this coverage, the carrier agrees to pay whatever it actually costs to rebuild your home, even if that exceeds your stated dwelling limit.
No percentage caps.
No buffers.
No guessing.
We explained this in Guaranteed Replacement Cost Explained, including why this coverage is rare, highly underwritten, and typically reserved for well-maintained homes with preferred carriers.
This is the strongest valuation protection available.
But it must be in place before a loss.
It cannot be added afterward.
The Other Side of the Coin: Actual Cash Value (ACV)
Now let’s talk about where claims quietly fall apart.
Actual Cash Value means:
Replacement Cost. Depreciation = Your payout
Age and wear reduce your check.
A 15-year-old roof doesn’t get paid like new.
Old flooring gets discounted.
Cabinets are valued based on remaining life.
This is one of the biggest claim surprises we see.
Homeowners assume insurance restores their home.
Instead, ACV restores part of the value.
We walked through this in Actual Cash Value vs. Functional Replacement Cost Explained, including why ACV dramatically reduces payouts after losses.
ACV is common on:
-
Older homes
-
Roof endorsements
-
Rental properties
-
Budget policies
It lowers premiums, but shifts risk back to the homeowner.
Functional Replacement Cost: Restoring Use, Not Appearance
Functional Replacement Cost sits between ACV and true Replacement Cost.
Instead of depreciating, the policy pays to restore function using modern, lower-cost materials.
Examples:
-
Drywall replaces plaster
-
Stock cabinets replace custom
-
Laminate replaces hardwood
The home becomes livable again, but not identical.
This can be appropriate for older homes with obsolete materials, but many homeowners don’t realize they’re on this valuation method until after a claim.
Again, it’s not wrong coverage.
It’s dangerous coverage if it’s accidental.
Putting It All Together: The Valuation Ladder
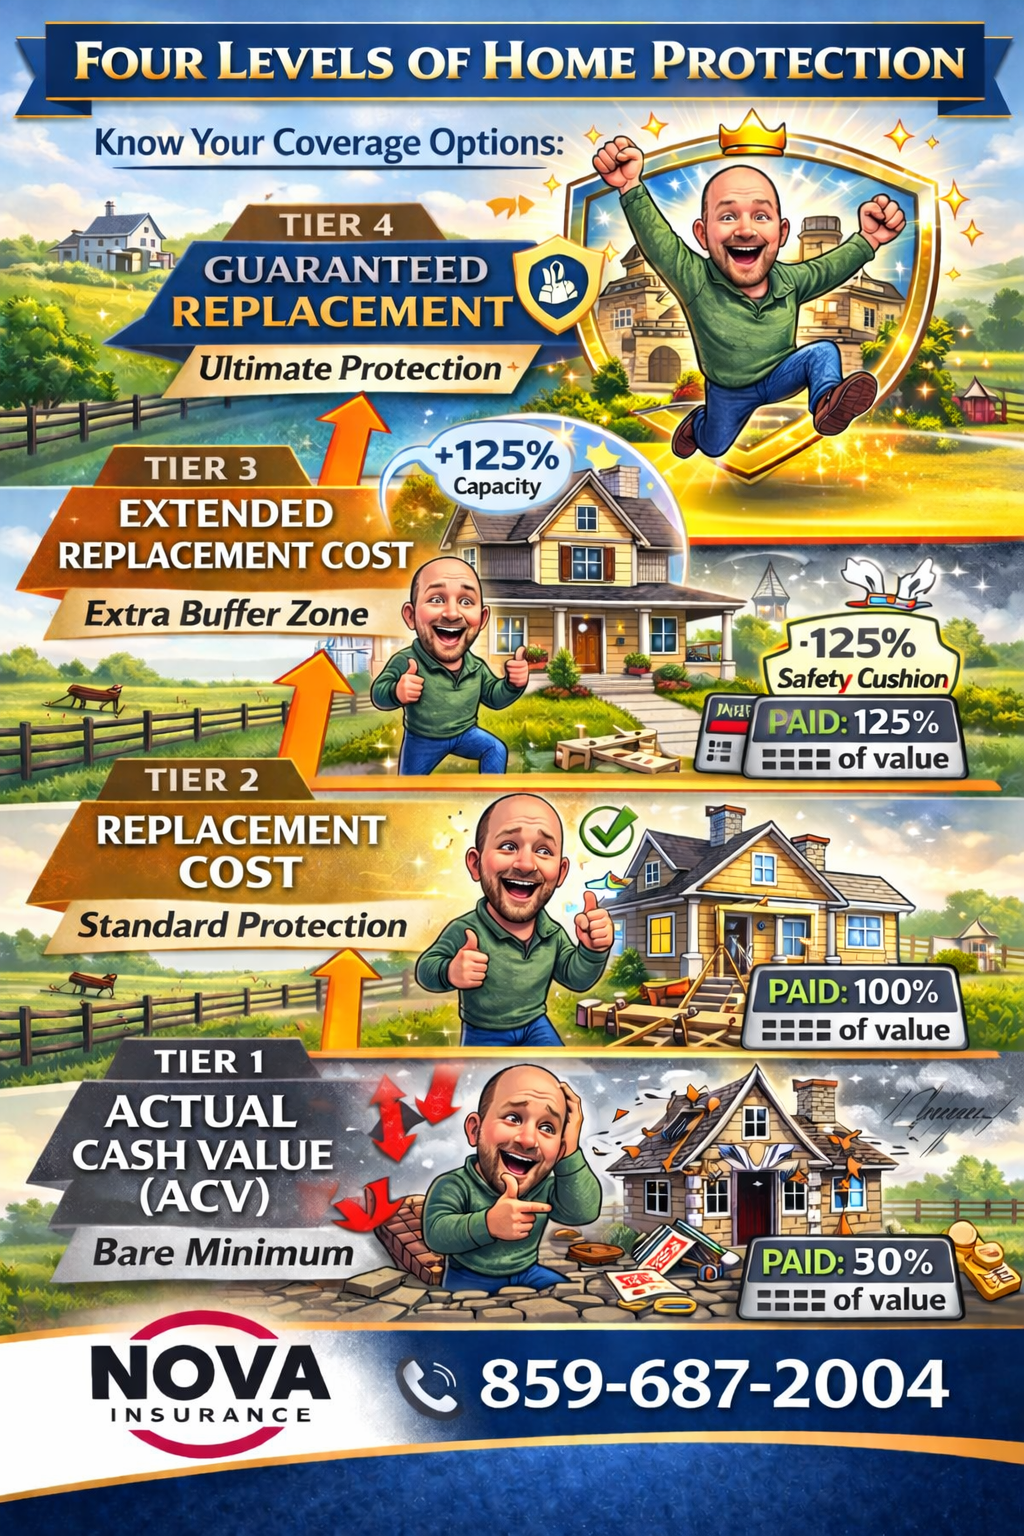
Here’s the full hierarchy from weakest to strongest:
-
Actual Cash Value (depreciated)
-
Functional Replacement Cost (function over finish)
-
Replacement Cost (no depreciation, limit applies)
-
Extended Replacement Cost (+25% / +50% buffer)
-
Guaranteed Replacement Cost (no ceiling)
Each step up reduces financial uncertainty.
Each step down increases homeowner exposure.
Why This Matters More Than Ever
Construction costs don’t rise slowly anymore.
They jump.
Even small projects feel it.
After major losses, demand surges and pricing follows.
That’s why valuation strategy matters just as much as coverage type.
You can be “insured” and still underpaid.
How to Know What You Have
Ask these questions:
-
Is my dwelling Replacement Cost or ACV?
-
Do I have Extended Replacement Cost? How much?
-
Is Guaranteed Replacement Cost available?
-
Are any components ACV only (like roofs)?
-
Has my rebuild estimate been updated recently?
If you don’t know the answers, you’re not alone.
Most homeowners don’t.
Ready to Review Your Home’s Valuation?
This entire series comes down to one thing:
Understanding your valuation before a loss.
At Nova Insurance Group, we help homeowners understand:
-
Which valuation method they currently have
-
Where depreciation may apply
-
Whether Extended or Guaranteed Replacement Cost is available
-
How rebuild costs compare to coverage
👉 Start your coverage review here.
Or call us directly at 859-687-2004.
Because rebuilding your home shouldn’t involve financial guesswork.
Final Takeaways
-
Replacement Cost is the foundation, but not unlimited
-
Extended Replacement Cost adds a critical safety buffer
-
Guaranteed Replacement Cost removes the ceiling entirely
-
ACV and Functional Replacement reduce payouts
-
Valuation matters as much as coverage
-
Reviews prevent expensive claim surprises
Next week, we’ll continue building on this foundation with practical scenarios and coverage strategies every Kentucky homeowner should understand.
Video Transcript: Home Insurance Valuation: The Four Levels
There are four ways home insurance can pay when your house gets damaged.
Three of them are bad.
One is good.
Most homeowners have no idea which one they have.
Here’s the ladder. Worst to best.
Level one, ACV. Actual Cash Value.
They depreciate everything.
Twelve-year-old roof? Pennies on the dollar.
Level two. Replacement Cost.
They pay what it costs to replace today.
Better. But there’s a ceiling, your dwelling limit.
Level three. Extended Replacement Cost. ERC.
Your dwelling limit plus a 25 or 50 percent cushion.
A three-fifty policy stretches to four-thirty-eight or five-twenty-five.
Costs about ten bucks a month.
Level four. Guaranteed Replacement Cost. GRC.
There IS no ceiling.
Whatever it costs to rebuild, the carrier pays.
Not every carrier offers it. Your home has to qualify.
Most older policies are stuck on ACV or Replacement Cost.
A handful are on ERC.
Almost nobody asks for GRC.
If your policy was set up in 2018 and you’ve been paying premiums on autopilot ,
you’re probably under-protected by a lot.
Pull your declarations page right now.
Find the line that says “Loss Settlement” or “Dwelling Coverage Type.”
Then call Nova. 859-687-2004.
We’ll tell you which level you’re on, and which level you should be on.
Free. Five minutes.
That’s what an agent who works for YOU does.
Written by Steve Straub, COO of Nova Insurance Group and a licensed Kentucky insurance agent (NPN 19734248). This article is general information current as of February 2026. Your coverage depends on your policy and insurance company. Questions? Call 859-687-2004 or email team@novainsurancegroup.com.
